2026 Canada Mortgage Cliff: Protect Your Renewal
Mortgage Renewal, Canada Mortgage Cliff, Fixed Vs Variable Rates, OSFI Regulations, Equity Negotiation, Interest Rate Strategy
The 2026 Canada Mortgage Cliff: A Four-Step Strategy to Protect Your Renewal
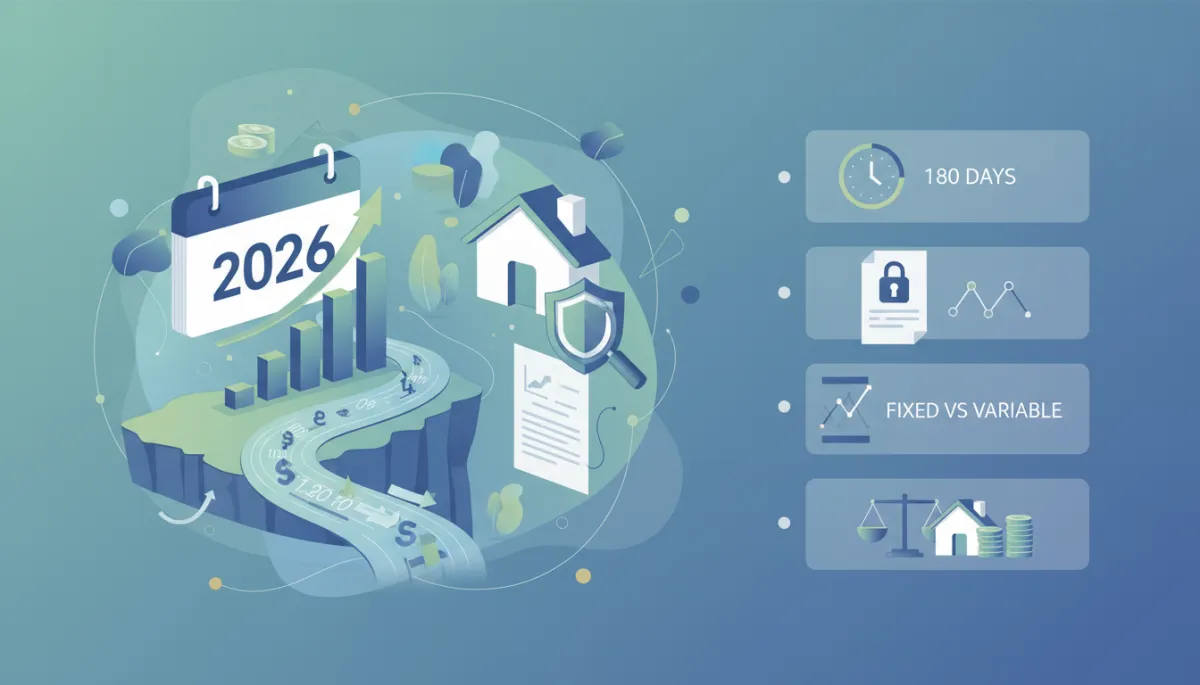
Roughly 1.2 million Canadian households are heading toward a 2026 “Mortgage Cliff” as low-rate pandemic mortgages reset to today’s higher interest rate environment. For homeowners in the Greater Toronto Area, especially first-time buyers and owners of affordable homes and condos, planning your mortgage renewal isn’t optional—it is a critical financial strategy. The Affordable Homes and Condos - Ali Bolourchi Real Estate (A.B.R.E.) Team has put together a four-step framework to help you manage your mortgage renewal strategically, protect your budget, and make the most of your home equity.
Why the 2026 Mortgage Cliff Matters for GTA Homeowners
The Bank of Canada estimates that about 60% of Canadian mortgages will renew between 2025 and 2026, with many households facing payment increases of around 20% on five-year fixed terms taken during the ultra-low-rate pandemic years (Bank of Canada). In the Toronto area, where home prices and loan-to-value ratios tend to be higher, this “Canada Mortgage Cliff” is especially important for budget-conscious owners of condos and entry-level homes.
As of September 2026, typical insured mortgage rates across Canada are roughly:
5-Year Fixed: approximately 3.84%–4.04% (typical range based on discounted insured rates around 4.06%–4.39%) (Ratehub, WOWA)
5-Year Variable: approximately 3.30%–3.35% (in line with insured variable offers around 3.25%–3.45%)
With variable rates still cheaper than fixed, but volatility and OSFI regulations in play, a clear interest rate strategy becomes essential. Here is a four-step framework from the A.B.R.E. Team to help you manage your mortgage renewal instead of being surprised by it.
Step 1: Start Mortgage Renewal Preparations 180 Days Before Maturity
Legally, your lender only has to give you 21 days’ notice before your mortgage term ends. Waiting until then, however, puts you in a weak negotiating position and leaves almost no time to explore alternatives. For households facing the 2026 Canada Mortgage Cliff, we recommend starting preparations at least 180 days (six months) before your maturity date.
Review your current payment, remaining amortization, and outstanding balance.
Estimate what your payment could look like at today’s 5-Year Fixed and 5-Year Variable rates.
Check your credit, other debts, and monthly budget to see what level of increase you can realistically absorb.
💡 Pro Tip: Use this six-month window to speak with a mortgage professional and a real estate advisor together. The A.B.R.E. Team can help you understand how your renewal choices affect your long-term housing plans in the GTA.
Step 2: At 120 Days Out, Secure a Rate Hold and Gather Key Documents
Around 120 days before your maturity date, you move from “planning” to “protecting.” This is when you should:
Locate your original mortgage commitment letter. This document outlines your original rate, term, amortization, prepayment options, and sometimes how your mortgage was registered (Standard vs. Collateral Charge). It is your baseline for comparing new offers and understanding what has changed.
Secure a rate hold. Many lenders and brokers can lock in a rate for up to 120 days. If 5-Year Fixed rates are in the 3.84%–4.04% range and you are worried about a spike, a rate hold protects you. If rates drop before renewal, you can often still switch to the lower option—so a rate hold is a one-way safety net, not a trap.
In a period where interest rates are influenced by global energy prices and bond yields, locking in a competitive rate ahead of time is a core interest rate strategy. It allows you to focus on other decisions—such as Fixed Vs Variable Rates and term length—without the pressure of sudden market moves.
Step 3: Compare Fixed Vs Variable Rates and Understand VRM vs ARM Mechanics
With 5-Year Fixed rates currently around 3.84%–4.04% and 5-Year Variable near 3.30%–3.35%, it is tempting to simply choose the lowest number. But the right choice depends on how payments behave over time and how much volatility you can handle.
Benefits of Fixed Rates: Payment Stability
A Fixed Rate gives you:
Predictable payments for the full term—ideal if your budget is tight or you are a first-time buyer adjusting to ownership costs.
Protection from future rate increases, which is reassuring in an uncertain economic environment.
The trade-off is that you may pay a bit more upfront compared with a variable, and breaking a fixed mortgage early can sometimes mean higher penalties.
Benefits of Variable Rates: Lower Cost with Volatility Exposure
A Variable Rate is tied to your lender’s prime rate (currently around 4.45% across major banks). Historically, variable has often cost less over the full term, and as of fall 2026, the gap between Fixed Vs Variable Rates still favours variable by roughly half a percentage point in many cases.
You could save interest if the Bank of Canada holds or cuts rates.
Penalties to break a variable term are often lower (typically three months’ interest).
The downside is rate volatility exposure. If prime rises, so will your cost—either through higher payments or a longer amortization, depending on your mortgage type.
VRM vs ARM: Trigger Rates and How Your Payment Reacts
Not all variable mortgages behave the same. Understanding this is crucial for anyone renewing into, or out of, a variable product:
VRM (Variable-Rate Mortgage, fixed payment): Your payment stays the same when prime changes, but the portion going to interest vs. principal adjusts. If rates rise enough, you can hit a trigger rate—the point where your payment barely covers interest. At that stage, the lender may increase your payment, extend your amortization, or require a lump-sum payment.
ARM (Adjustable-Rate Mortgage): Your payment changes whenever prime changes, keeping your amortization more stable. You feel rate moves right away in your monthly budget, but you are less likely to silently build up negative amortization.
During the pandemic rate hikes, many VRM borrowers in Canada hit their trigger rates, and OSFI flagged this segment as higher risk. As you approach renewal, clarifying whether you hold a VRM or ARM—and how each lender structures these products—should be part of your Mortgage Renewal conversation.
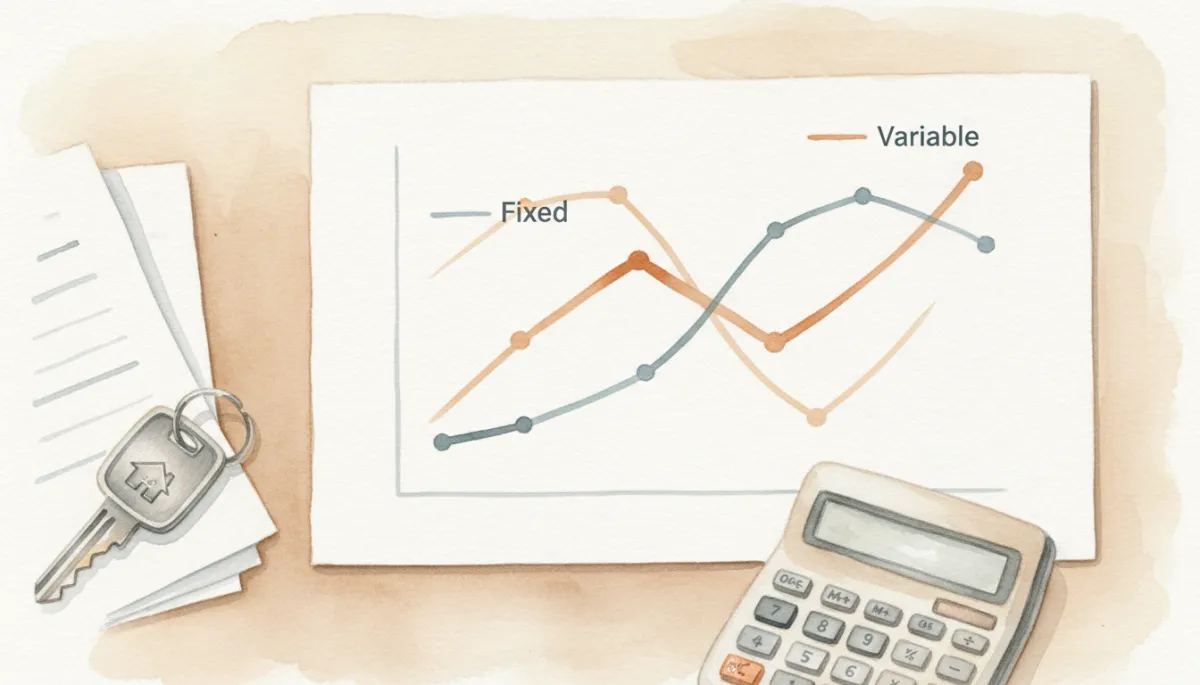
Visualizing fixed versus variable payments helps homeowners choose a strategy they can live with.
Step 4: Understand OSFI Regulations, Registration Type, and Use Equity to Negotiate
Standard vs. Collateral Charge Registration
How your mortgage is registered on title affects your flexibility at renewal:
Standard Charge: Easier to transfer (“switch”) to another lender at renewal with minimal legal costs. This can increase your bargaining power because you can move your mortgage more easily if a competitor offers better terms.
Collateral Charge: Often allows you to re-borrow up to a higher amount under the same charge, but switching lenders can require a full refinance, with new legal fees and, often, a fresh stress test. Many borrowers discover this only at renewal, when it limits their options.
The OSFI “Straight-Switch” Rule: Transferring Without a New Stress Test
Canada’s banking regulator, OSFI, has updated rules to make it easier for borrowers to shop around at renewal. Under the newer “straight-switch” guideline, if you are simply transferring your mortgage to a new lender at renewal—without increasing the principal, extending the amortization, or changing key terms—many lenders can accept you without applying a new mortgage stress test.
This is a crucial protection during the 2026 Canada Mortgage Cliff. It means that even if today’s qualifying rate would normally be too high for your income, you may still be able to move to a lender offering a better 5-Year Fixed or 5-Year Variable rate, as long as the switch is “straight” and terms remain identical. Always confirm how your preferred lender applies OSFI regulations in practice.
Get an Accurate Property Valuation to Establish Your Equity Baseline
Your home equity—the difference between your property’s market value and your mortgage balance—is one of your strongest tools in renewal negotiations. With some GTA neighbourhoods experiencing price declines from peak levels, many owners are unsure how much equity they truly have.
A professional market valuation (from a knowledgeable real estate agent) gives you a realistic price estimate based on recent sales of similar homes or condos in your area.
This valuation helps your mortgage professional determine your loan-to-value (LTV) ratio, which directly affects the rates and products you qualify for.
For example, if your updated valuation shows you have more than 20% equity, you may qualify for better conventional rates or have more leverage to negotiate prepayment privileges, lump-sum options, or a shorter amortization. If your equity is thinner, knowing that early gives you time to adjust expectations or consider strategies like extending amortization to keep payments affordable.
The A.B.R.E. Team specializes in affordable homes and condos across the Greater Toronto Area and can provide a data-driven valuation that supports strong equity negotiation with your current lender or a competing institution.
Putting It All Together: A Calm, Strategic Path Through the 2026 Mortgage Cliff
Facing a major Mortgage Renewal in 2026 does not have to mean panic. By starting preparations 180 days before maturity, securing a rate hold 120 days out, carefully weighing Fixed Vs Variable Rates (and VRM vs ARM structures), and using OSFI Regulations and your equity position to negotiate, you can turn a potential shock into a manageable transition.
For first-time buyers and affordability-focused owners in the GTA, the key is not to wait for your lender’s 21-day notice. Instead, treat your renewal like any other major financial decision—one that deserves time, information, and professional guidance.
The Affordable Homes and Condos - Ali Bolourchi Real Estate (A.B.R.E.) Team is committed to transparency, client empowerment, and digital innovation. We can help you:
Understand your renewal options in plain language and align them with your long-term housing goals.
Obtain an accurate, neighbourhood-specific valuation for your condo or home to support strong equity negotiation.
Explore affordable listings if your renewal prompts a move to a more budget-friendly property.
Next Steps: Take our free First-Time Home Buyer Eligibility Quiz, browse current affordable homes and condos in your preferred GTA neighbourhoods, download our buyer’s and seller’s guides, or contact the A.B.R.E. Team for personalized renewal and interest rate strategy support tailored to your situation.